Big Spring School District audit returns clean opinion; auditors note prior-year single-audit timing finding
Summary
Boyer & Ritter presented the district's 2024–25 audited financial statements and issued an unmodified (clean) opinion while noting a prior-year single-audit submission timing finding; auditors also highlighted a GASB 101-driven increase in compensated-absence liabilities.
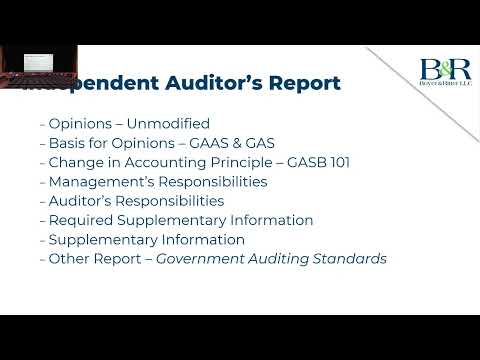
Boyer & Ritter presented Big Spring School District's 2024–25 financial statements and issued an unmodified audit opinion, the auditors said during the Feb. 17 board meeting. "We've issued an unmodified opinion," auditor Sahi Zaherich said, calling it "the best possible result" for the engagement.
The firm also reported a separate internal-control finding tied to the 2024 single-audit not being submitted within the federal nine-month deadline; Zaherich said the 2024–25 audit was completed within the nine-month window, which resolves the timing finding for the year under review. The auditors tested the child nutrition cluster as the major federal program and reported an unmodified compliance opinion on that program.
Zaherich highlighted note-level changes tied to new accounting guidance, saying implementation of GASB 101 changed how compensated absences are measured and increased the district's reported liability. He told the board the compensated-absence liability rose materially year-to-year because of that accounting change. The presentation also summarized fund-level results, including a reported general-fund ending balance of about $22 million for 2025 and a capital-reserve balance the presentation showed around $13.1 million.
Board members thanked the audit team and approved a motion accepting the 2024–25 financial statements and audit and authorizing administration to distribute the reports as required. The motion carried in the meeting without a roll-call tally printed in the transcript.
What happens next: administration will post the audit package per bond-disclosure and state requirements and work with the auditors to implement management-letter recommendations and any accounting-model changes for future reporting.
AI generated
The text on this page is AI generated. Summaries, highlights, analysis, and video transcripts are all produced from the original source material.
AI can make mistakes, so if you spot one, and we will fix it for everyone.
Note: the source content is unaltered by us. Any content source we link to, be it a video, an audio recording, or a document, is presented exactly as its publisher released it. That publisher is usually a government body, sometimes an individual official or another organisation.