Get email alerts on the County Audit topic
No spam. Unsubscribe anytime.
County auditor reports clean opinion but flags repeat material weaknesses
Summary
The county's annual audit received an unmodified (clean) opinion, auditor Nate Baldererman told commissioners, but the audit identified four repeat material weaknesses in internal controls and several comments and recommendations; major programs tested included ARPA and Child Support Services.
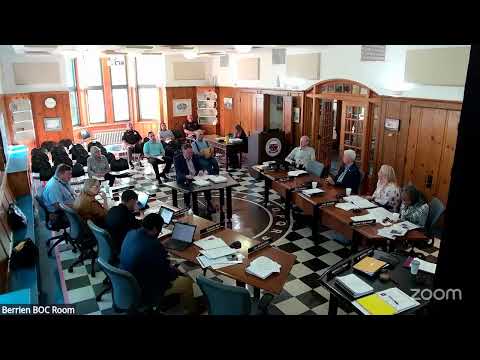
The county's financial statements received an unmodified (clean) audit opinion, auditor Nate Baldererman told the Berrien County Board of Commissioners, but the audit also identified repeat material weaknesses that officials must address.
Baldererman said an unmodified opinion means the financial statements are "fairly stated in all material respects." He explained auditors also evaluate internal controls and, while an opinion on financial statements is separate from an assessment of internal controls, the audit this year identified four material weaknesses related to internal control over financial reporting and several repeat findings.
The auditor said the single‑audit scope included two major programs this year: ARPA (American Rescue Plan Act) funds and the Child Support Services program; testing produced unmodified compliance opinions for those programs. He noted one significant deficiency related to documentation of review and approval over federal reporting processes and seven comments and recommendations (four repeat items and three new items).
Baldererman described common repeat items such as documentation around purchase orders and vendor checks and said the audit team continues to work with department leadership—citing the road department as an example of a long‑running remediation target. He warned that changes proposed to the Uniform Guidance and the compliance supplement could affect grant monitoring and audit procedures and urged officials to keep policies and procedures current.
Commissioners asked about whether audit findings affect the county's bond rating; the auditor and a commissioner said ratings are driven primarily by the unmodified opinion and the underlying financial ratios, reserves and liabilities, not by isolated findings. The auditor closed by reiterating that management should document review processes to reduce repeat findings in future audits.
AI generated
The text on this page is AI generated. Summaries, highlights, analysis, and video transcripts are all produced from the original source material.
AI can make mistakes, so if you spot one, and we will fix it for everyone.
Note: the source content is unaltered by us. Any content source we link to, be it a video, an audio recording, or a document, is presented exactly as its publisher released it. That publisher is usually a government body, sometimes an individual official or another organisation.