Audit: Big Spring posts clean 2023–24 audit, $5.1M positive fund-balance variance
Summary
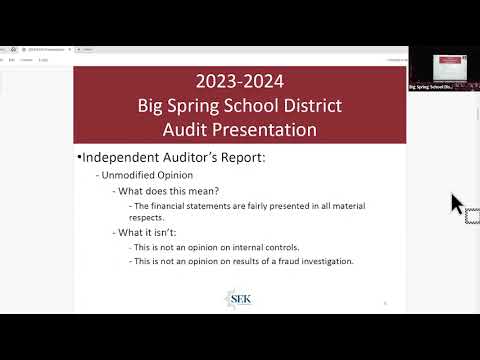
Auditors issued an unmodified opinion on Big Spring School District's 2023–24 financial statements, reporting about $65.7M in general-fund revenues, a $5.1M increase in fund balance (versus a budgeted $521K deficit), and no findings in the financial-statement or single audits.
Auditors from Smith Elliot Curren (SK) told the Big Spring School District board that the 2023–24 financial statements received an unmodified (clean) opinion and that both the financial‑statement audit and the single audit produced no findings.
Kevin Stalford summarized core metrics: total general‑fund revenues of about $65.7 million (roughly a 4.7% increase from the prior year), total expenditures near $60.7 million, and an overall change in fund balance of approximately $5.1 million compared with a budgeted deficit of $521,000 — a positive variance of roughly $5.6 million. He also flagged a one‑time payment of about $2.4 million that raised instruction spending for the year and explained that a prior $4.2 million transfer to the capital reserve inflates some multi‑year comparisons.
Stalford noted federal expenditures for 2023–24 were just under $3.9 million and that the child‑nutrition cluster was tested as part of the single audit with no findings. He also reported the food‑service fund was essentially self‑sustaining with a positive change in net position of about $28,000. The auditor said: "we were able to issue an unmodified audit opinion," adding that the opinion means the statements are materially correct and can be relied upon but does not constitute an opinion on internal controls or detect every instance of fraud.
Board members asked for clarifications about how cyber‑school students are included in instruction totals, whether reported figures include late refunds, and when the next audit cycle will begin; Stalford said field work for the 2024–25 audit was scheduled for late September/early October with final results expected later in the winter and that the district will be transitioning to a different audit firm for future years.
AI generated
The text on this page is AI generated. Summaries, highlights, analysis, and video transcripts are all produced from the original source material.
AI can make mistakes, so if you spot one, and we will fix it for everyone.
Note: the source content is unaltered by us. Any content source we link to, be it a video, an audio recording, or a document, is presented exactly as its publisher released it. That publisher is usually a government body, sometimes an individual official or another organisation.